Insurance Documentation After Property Damage
A burst supply line can soak flooring before sunrise. A kitchen fire can leave smoke residue in rooms that look untouched. In moments like these, insurance documentation is more than paperwork - it is the record that helps explain what happened, what was affected, and what work was needed to protect the property.
For homeowners, property managers, and business owners in El Paso, good documentation helps keep communication clear when the situation is anything but. It can support your insurance claim, help restoration professionals build an accurate scope of work, and reduce avoidable delays as cleanup and repairs move forward.
Start Documentation Before Cleanup Changes the Scene
Safety comes first. If there is an active leak, electrical hazard, structural concern, sewage backup, fire damage, or suspected biohazard exposure, do not enter an unsafe area just to take pictures. Call for emergency help when needed, and take reasonable steps to prevent further damage once it is safe to do so.
That does not mean waiting for an adjuster before beginning emergency mitigation. Standing water, wet building materials, and smoke residue can cause additional damage when left in place. The goal is to document conditions promptly, then stabilize the property with appropriate professional care.
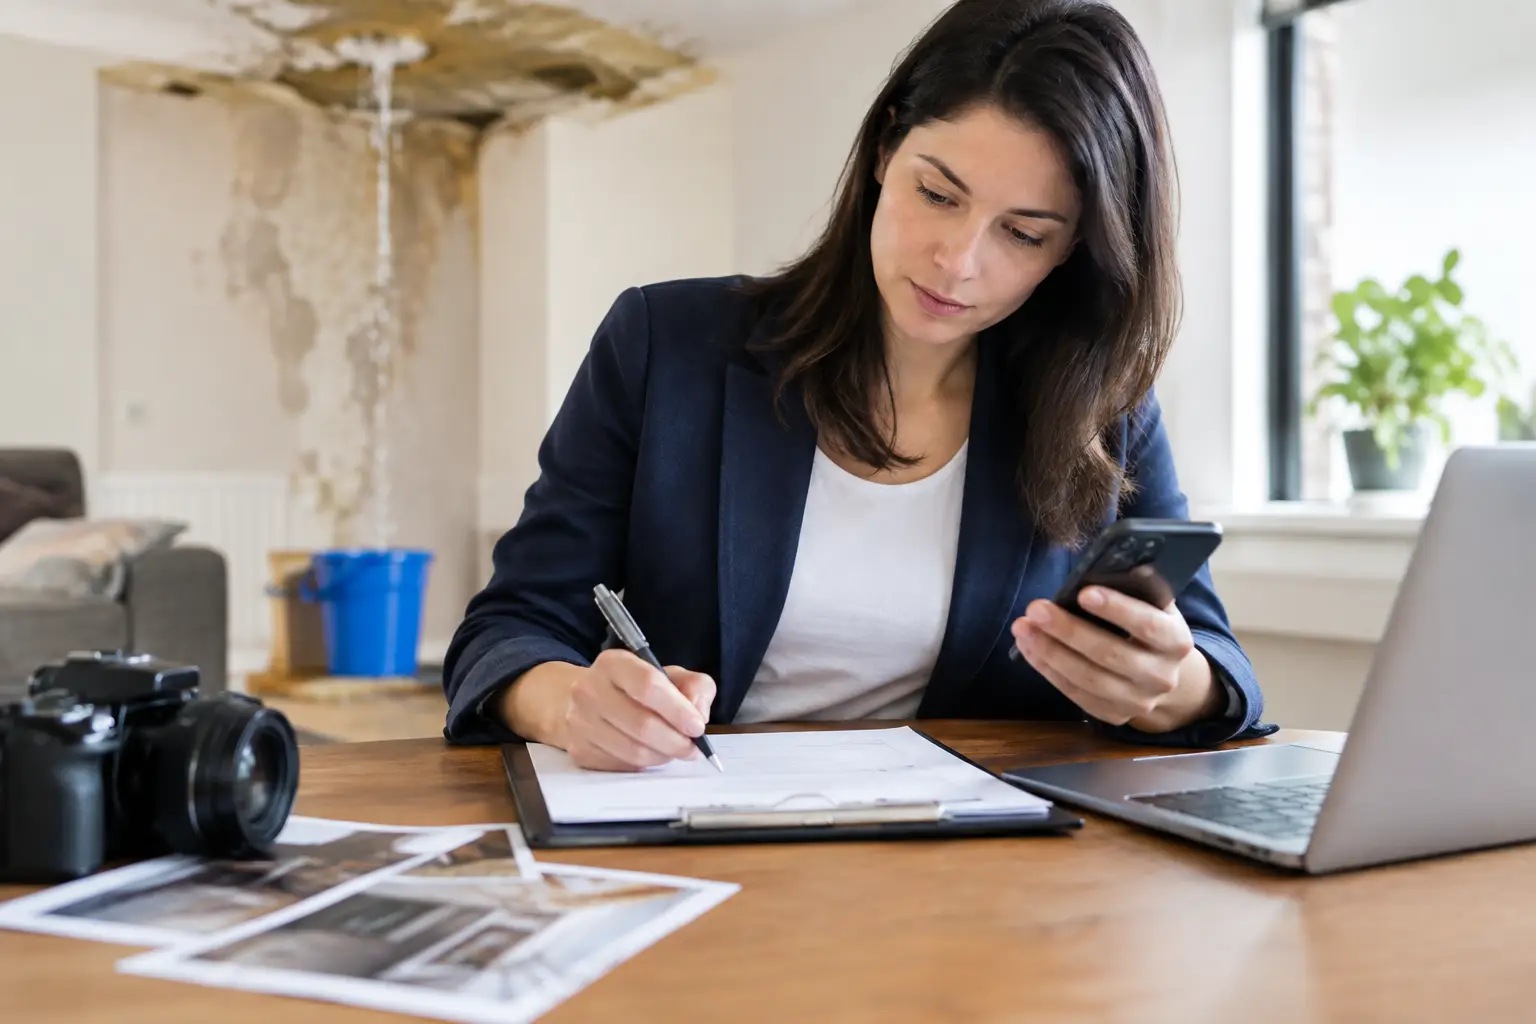
Take photos and video from wide angles first. Capture each affected room, the apparent source of damage if visible, and the condition of walls, floors, ceilings, furniture, and belongings. Then take closer images of damaged materials, water lines, appliance connections, soot, staining, warped flooring, or mold-like growth.
Use your phone's date and time settings, and avoid editing original images. If possible, save copies in a cloud folder or send them to an email address you can access later. A damaged phone, lost device, or chaotic cleanup should not erase the only record of your loss.
What Strong Insurance Documentation Includes
A clear claim file tells the story of the loss from the first emergency call through completed reconstruction. Every claim and policy is different, but the most useful records usually include a combination of visual evidence, written notes, professional reports, and financial documents.
Keep a simple log that records the date and time you discovered the damage, what you observed, steps you took to limit further loss, and every person or company you spoke with. Include claim numbers, adjuster names, phone numbers, and a brief note about what was discussed. This is especially helpful when several weeks pass between the initial emergency and final repairs.
For major losses, gather these materials in one place:
- Photos and videos of damaged areas and personal property before disposal or removal
- A room-by-room inventory of affected belongings, including approximate age, brand, model, and estimated value when known
- Receipts, invoices, estimates, work authorizations, and proof of emergency expenses
- Emails, text messages, claim correspondence, and notes from calls with your insurer or adjuster
- Professional moisture readings, drying logs, inspection findings, cleaning records, and reconstruction scopes when applicable
Do not worry if you cannot identify every item immediately. Fire, water, and smoke losses are stressful, and memory is imperfect under pressure. Start with high-value items, essential business equipment, electronics, furniture, and anything with a serial number or receipt. Add to the inventory as you remember more.
Why Professional Records Matter
A restoration project involves details that may not be visible after the first day. Wet drywall can look normal on the surface while moisture remains behind it. Smoke particles can travel through air systems and settle in cabinets, textiles, and adjoining rooms. A qualified restoration team documents these conditions with appropriate tools and job records.
For water damage, this may include moisture maps, daily drying documentation, equipment logs, affected-material records, and photos of containment or removal work. For fire and smoke damage, records may include cleaning methods, soot conditions, odor-control measures, and documentation of materials that could not be restored safely. For mold-related work, inspection findings, containment steps, clearance-related documentation when applicable, and records of the underlying moisture source can all matter.
These records are not meant to overwhelm property owners. They create a factual trail for the work performed and the conditions that made it necessary. They also help protect against misunderstandings after walls are closed, flooring is replaced, or contents are returned.
Document the Damage, Not Just the Dramatic Parts
It is natural to photograph the collapsed ceiling or flooded living room. Those images matter, but less obvious damage can be just as significant. Water can affect baseboards, insulation, cabinets, subflooring, and rooms below or beside the original source. Smoke from a small fire may travel beyond the room where flames started.
Walk through the property methodically when it is safe. Photograph each room, including rooms that appear unaffected. Note unusual odors, visible residue, bubbling paint, damp carpet edges, warped doors, or changes in ceiling texture. For a commercial property, include offices, storage areas, inventory spaces, equipment rooms, common areas, and any interruption to operations.
If the incident affects business operations, document lost access, damaged equipment, canceled reservations or appointments, and emergency purchases made to keep the business functioning. Whether those items are covered depends on the policy, but accurate records give you and your insurance representative a clearer starting point.
Avoid Common Documentation Mistakes
The biggest mistake is often waiting too long. Damage changes quickly, especially in El Paso heat or after a plumbing loss. Take initial photos as soon as conditions are safe, even if they are not perfect. You can always add better documentation later.
Another common problem is throwing away damaged materials too early. Some materials must be removed quickly for health, safety, or drying reasons, so do not keep unsafe debris in place. Instead, photograph the item, note why it was removed, and retain samples only when your restoration professional or insurer advises it is appropriate.
It also helps to separate facts from assumptions. Write, “Water was found under the vanity and along the hallway baseboard,” rather than guessing at the full cause or extent of damage. Professional inspection and insurance review can determine the details. Clear observations are more useful than speculation.
Finally, do not rely solely on verbal conversations. Follow up important discussions with a short email or written note: the date, who you spoke with, and what was agreed upon. This is not confrontational. It is simply good property management during a complicated event.
Coordinate Restoration Work With Your Claim
Insurance documentation works best when the property owner, insurance carrier, and restoration team have a consistent picture of the loss. Prompt mitigation can help prevent additional damage, while detailed job records explain the emergency services performed. The repair scope can then address reconstruction needs after drying, cleaning, removal, or remediation is complete.
Coverage decisions remain with your insurance carrier and depend on your policy, deductible, cause of loss, limits, exclusions, and endorsements. A restoration contractor should not promise coverage or tell you what your insurer must pay. What a qualified team can do is document the damage thoroughly, provide clear estimates and records, and communicate professionally with the parties involved.
This coordination is especially valuable when one event requires several stages of work: emergency water extraction, drying, material removal, cleaning, repairs, and rebuilding. Working with separate vendors can create gaps in records or confusion about who handled each phase. An end-to-end team can keep the job file organized from stabilization through reconstruction.
GEM Disaster Recovery Corp helps El Paso property owners document emergency conditions and restoration work while providing the practical guidance needed to move from damage toward recovery.
Keep a Claim Folder Until the Work Is Complete
Create one physical folder, one digital folder, or both. Place your policy information, claim number, correspondence, photos, inventory, invoices, estimates, and restoration records there. Name digital files clearly, such as “Kitchen water damage - March 12 - before extraction.” Small organizational steps make a major difference when an adjuster, lender, property owner, or accountant needs information later.
Keep records after the work is done as well. Final invoices, paid receipts, warranties, repair photos, and any completion documents can be useful for future property sales, maintenance questions, or tax discussions with a qualified professional.
When property damage disrupts your home or business, you do not need to become an insurance expert overnight. Focus on safety, document what you can, save every record, and ask for clear explanations along the way. A well-documented loss gives everyone involved a better foundation to restore the space with care.